


We surveyed over 500 retirees and near-retirees to identify their top concerns, including guaranteed income, low fees, and service quality. We also interviewed licensed annuity agents nationwide to learn which companies are the most reliable and easiest to work with. Finally, we evaluated each provider using hard data, including annuity company ratings, total premiums sold and more. Every company was scored across these three dimensions to produce a well-rounded, trustworthy ranking.
- New York Life — Lifetime Income Stability
New York Life is the gold standard for retirees who prioritize safety and guaranteed lifetime income above all else. - Allianz — Best for Growth-Oriented Index Strategies
With a market-leading lineup of fixed index annuities, Allianz is ideal for buyers who want downside protection with meaningful upside participation through innovative crediting strategies. - Nationwide — Top Annuity Variety
Nationwide offers one of the broadest annuity product ranges in the industry, paired with competitive lifetime income riders featuring bonus credits of up to 30%. - Lincoln Financial Group — Best for Retirement Income Planning
Lincoln Financial holds an A+ AM Best rating and stands out for its robust suite of income-focused annuities and comprehensive advisor tools, making it a strong choice for retirees building a guaranteed paycheck. - MassMutual — Best for Conservative, Safety-First Investors
One of only a handful of A++-rated annuity carriers by AM Best, MassMutual’s mutual ownership structure means profits flow back to policyholders—perfect for conservative savers who value stability over yield.
Below, you’ll find detailed profiles for the top 5 companies to help you compare what matters most.
New York Life: Lifetime Income Stability
New York Life
Key Company Metrics
AM Best Rating: A++ (Superior)
Years in Business: 181 years
Direct Premiums Sold: $21.3 Billion
Product Availability: Fixed, Indexed, Immediate
“Their immediate and deferred income annuities are among the strongest in the market in terms of payout and stability.”
New York Life’s Strengths
| Financial Stability | ⭐⭐⭐⭐⭐ |
| Product Availability | ⭐⭐⭐⭐☆ |
| Customer Trust | ⭐⭐⭐⭐⭐ |
| Ease of Working with Agents | ⭐⭐⭐⭐☆ |
| Legacy & Lifetime Income | ⭐⭐⭐⭐⭐ |
Pros & Cons
Pros
- A++ AM Best, perfect 100 Comdex score
- Mutual company — answers to policyholders, not shareholders
- #1 income annuity payouts (LIMRA, every year since 2006); lowest complaint index in the category (0.04 overall)
Cons
- Captive agents only — no independent brokers, no online quotes/direct purchase
- Fixed/MYGA rates not publicly published — hard to comparison-shop
- Narrower indexed-annuity (FIA) lineup than specialists like Allianz
Consumer Poll Insights
Consumers consistently rank New York Life high for lifetime income guarantees, company longevity, and confidence in claims-paying ability.
- 73% prioritize financial strength when selecting a provider
- 65% say product transparency and clear payout terms are vital
Allianz: Growth-Oriented Index Strategies
Allianz
Key Company Metrics
AM Best Rating: A+ (Superior)
Years in Business: 130 years
Direct Premiums Sold: $23.1 Billion
Product Availability: Fixed, Indexed, Immediate
“Allianz offers some of the most innovative indexed annuities in the industry — strong cap rates, flexible riders, and consistent performance.”
Allianz’s Strengths
| Financial Stability | ⭐⭐⭐⭐☆ |
| Product Availability | ⭐⭐⭐⭐☆ |
| Customer Trust | ⭐⭐⭐⭐☆ |
| Ease of Working with Agents | ⭐⭐⭐⭐☆ |
| Innovation & Digital Tools | ⭐⭐⭐⭐⭐ |
Pros & Cons
Pros
- A+ rated, backed by $2.65T global insurer
- Led FIA sales for 5 consecutive years and remains a top-2 carrier today
- Below-average complaint index
Cons
- Illustrated “income value” ≠ actual cash value
- RILA fees: 1.25% + 0.70% for income rider
- 7–10 yr surrender period, 10% free withdrawal cap
Consumer Poll Insights
Allianz stands out for its indexed annuities, which balance growth potential with downside protection — a favorite among long-term planners.
- 70% of consumers value companies that offer customizable annuity options
- 64% prioritize online account access and modern digital tools
Nationwide: Top Annuity Variety
Nationwide
Key Company Metrics
AM Best Rating: A+ (Superior)
Years in Business: 100 years
Direct Premiums Sold: $12.85 Billion
Product Availability: Fixed, Indexed, Variable, Immediate
“Nationwide is incredibly consistent — applications are easy, and support is top-notch.”
Nationwide’s Strengths
| Financial Stability | ⭐⭐⭐⭐☆ |
| Product Availability | ⭐⭐⭐⭐⭐ |
| Customer Trust | ⭐⭐⭐⭐☆ |
| Ease of Working with Agents | ⭐⭐⭐⭐☆ |
| Flexibility & Innovation | ⭐⭐⭐⭐☆ |
Pros & Cons
Pros
- A+ (AM Best & S&P), Comdex 93/100 — top 7% of rated carriers
- Broadest lineup of the five: FIA, MYGA, variable, and immediate options
- Top-5 FIA seller nationally; strong lifetime-income rider options
Cons
- Long lock-up on flagship FIAs — Peak 10/12 carry 10–12 yr surrender periods
- MYGA rates trail top rate-specialist carriers
- Several products unavailable in NY/CA; independent agents only, no direct option
Consumer Poll Insights
Nationwide is often chosen for its broad selection of products, including variable annuities with flexible income riders and robust customization options.
- 69% of consumers want companies with a wide range of annuity types
- 61% are concerned about fees and long-term flexibility
Lincoln Financial: Retirement Income Planning
Lincoln Financial Group
Key Company Metrics
AM Best Rating: A (Excellent)
Years in Business: 121 years
Direct Premiums Sold: $27.1 Billion
Product Availability: Fixed, Indexed, Variable, Immediate, Deferred Income
“They’ve built a legacy of trust and perform well with high-net-worth clients seeking estate planning solutions.”
Lincoln Financial’s Strengths
| Financial Stability | ⭐⭐⭐⭐☆ |
| Product Availability | ⭐⭐⭐⭐⭐ |
| Customer Trust | ⭐⭐⭐⭐☆ |
| Ease of Working with Agents | ⭐⭐⭐⭐☆ |
| Retirement Income Planning | ⭐⭐⭐⭐⭐ |
Consumer Poll Insights
Lincoln is widely appreciated for income-focused annuities that provide long-term security, including options with inflation protection and death benefit riders.
- 68% say guaranteed lifetime income is a top priority
- 62% care about the company’s reputation for customer service
Pros & Cons
Pros
- A (Excellent) AM Best, A+ Fitch/S&P — solid across agencies
- Broadest true lineup: fixed, immediate, deferred, indexed, and variable
- Low complaint index (0.50)
Cons
- Limited public rate/fee transparency — hard to research independently without an agent
- Surrender charges run 2–9% during the guarantee period
- Variable annuity costs stack up: $35 fee + 0.95% M&E + up to 3.72% fund expenses
MassMutual: Conservative, Safety-First Investors
MassMutual
Key Company Metrics
AM Best Rating: A++ (Superior)
Years in Business: 175 years
Direct Premiums Sold: $9.09 Billion
Product Availability: Fixed, Indexed, Variable, Immediate
“MassMutual’s fixed annuities are among the most stable — ideal for clients who don’t want surprises.”
MassMutual’s Strengths
| Financial Stability | ⭐⭐⭐⭐⭐ |
| Product Availability | ⭐⭐⭐⭐☆ |
| Customer Trust | ⭐⭐⭐⭐⭐ |
| Ease of Working with Agents | ⭐⭐⭐⭐☆ |
| Conservative Planning Fit | ⭐⭐⭐⭐⭐ |
Pros & Cons
Pros
- A++ AM Best (highest possible), AA+ S&P/Fitch — held by only a handful of carriers
- Mutual company — 158 consecutive years of dividends ($2.9B planned for 2026)
- Exceptional capitalization: $33.2B surplus, $340B+ total assets
Cons
- MYGA rates lag competitors by roughly 100–120 basis points
- Career agents only — no independent broker access
- Parent-company vs. MassMutual Ascend subsidiary split creates confusion when comparing rates/products
Consumer Poll Insights
MassMutual is recognized for exceptional financial strength, making it a preferred choice for conservative retirees seeking safety and predictability.
- 71% of consumers trust companies with a long-standing track record
- 67% value financial strength ratings as a top priority
Best Annuity Company Ranking Methodology
Each company’s score from the three sources was normalized and weighted as follows:
- Measurable Metrics: 50% — AM Best financial strength rating, years in business, direct premiums sold, product variety, availability across states, NAIC complaint index & J.D. Power rankings and digital tools and online access.
- Consumer Survey: 25% — We surveyed over 500 retirees and near-retirees through an independent panel. Respondents ranked what mattered most to them when selecting an annuity provider.
- Agent Poll: 25% — We also gathered qualitative input from licensed annuity agents who actively write business with multiple carriers across the U.S. These experienced professionals ranked companies based on ease of doing business, product quality and flexibility, reputation and claims-paying ability and customer experience from the advisor’s point of view.
We then assigned each company a composite score and ranked the top performers. The final list reflects a balance of trustworthiness, product strength, service quality, and real-world experience — not just financial size or advertising dollars. More about our rankings can be found on our annuity rankings methodology page.
How to Compare Annuity Companies
We selected the top annuity companies based on what matters most to real buyers: financial strength, customer satisfaction, product flexibility, and advisor insights. However, while these rankings provide a strong starting point, the best company for you will ultimately depend on your unique goals, preferences, and retirement timeline.
Whether you value top-tier credit ratings, responsive support, or income guarantees, it’s important to weigh each provider against the factors that matter most to you.
The comparison chart below highlights key criteria to help you make a confident, personalized decision.
| ANNUITY COMPANY | AM BEST RATING | YEARS IN BUSINESS | PREMIUMS SOLD ($B) | PRODUCT TYPES OFFERED | BEST COMPANY FOR |
|---|---|---|---|---|---|
| New York Life | A++ | 180 | 21.3 | Fixed, Indexed, Immediate | Lifetime Income Stability |
| Allianz | A+ | 129 | 23.1 | Fixed, Indexed, Immediate | Growth-Oriented Index Strategies |
| Nationwide | A+ | 99 | 12.8 | Fixed, Indexed, Variable, Immediate | Top Annuity Variety |
| Lincoln Financial Group | A | 120 | 27.1 | Fixed, Indexed, Variable, Immediate, Deferred | Retirement Income Planning |
| MassMutual | A++ | 174 | 9.1 | Fixed, Indexed, Variable, Immediate | Conservative, Safety-First Investors |
Why the “Best” Company Isn’t the Same for Everyone
When it comes to choosing an annuity provider, there’s no one-size-fits-all answer. What works best for one person might not be the right fit for another, and that’s okay. Your financial priorities, comfort level with risk, need for flexibility, and desire for support all play a role in the decision.
Some people feel most confident choosing a provider with top-tier financial ratings. Others want hands-on guidance and flexible product features. Choosing the right annuity provider starts with knowing what matters most to you.
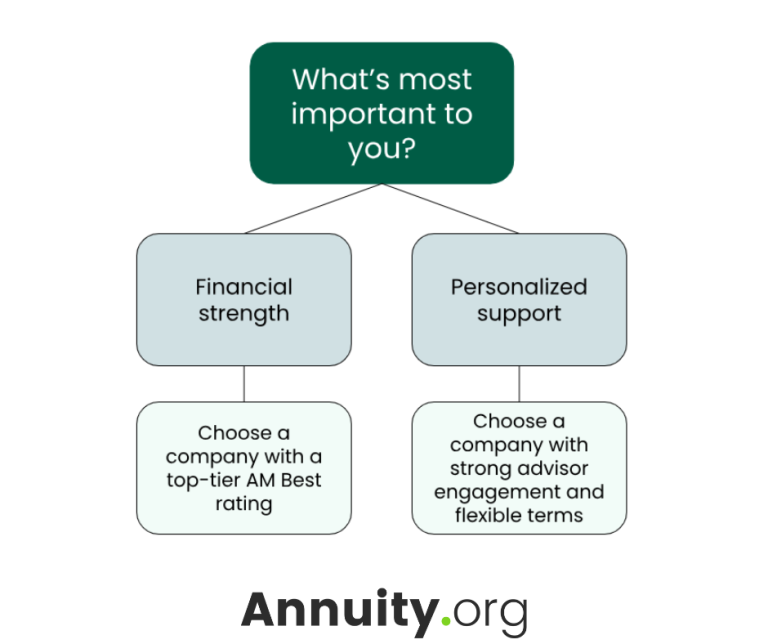
The following real-world scenarios show how different buyers made choices based on what mattered most to them, from long-term security to hands-on service and flexible income options. Use these examples to see how your own goals might align with different types of providers.
Choosing Based on Financial Strength and Service
Linda, a 63-year-old recently retired nurse, is looking for a fixed indexed annuity to secure lifetime income while keeping pace with inflation. She’s comparing two companies: Company A, a national brand with top-rated customer service and an A- AM Best rating, and Company B, a lesser-known insurer with an A++ rating but fewer online resources and less personalized support.
Linda is concerned about market volatility and wants to ensure her money is safe for the long haul. After speaking with her advisor, she decides on Company B because of its stronger financial strength rating and longer history in the annuity market. Even though Company A offered a slightly more user-friendly experience, Linda values long-term security and the confidence that her income stream is backed by a highly rated company with deep reserves.
Her decision reflects what many annuity buyers prioritize: financial stability over convenience, especially when retirement income is on the line.
Choosing Based on Personalized Support and Flexibility
David, a 58-year-old marketing consultant planning early retirement, wants a deferred fixed annuity that allows partial withdrawals and offers optional riders for long-term care. He’s deciding between Company X, known for its strong financials but limited customer contact options, and Company Y, which offers slightly lower ratings but assigns each client a dedicated advisor and offers more customizable rider options.
After requesting quotes, David is impressed that Company Y’s representative takes time to walk him through different income scenarios, explains how optional inflation protection works, and follows up with personalized illustrations tailored to his goals. He also learns that Company Y allows flexible withdrawal options without early surrender charges, which aligns with his plan to possibly start a side business.
Even though Company X had a higher AM Best rating, David chooses Company Y because of its responsive service, clarity around fees, and ability to tailor the contract to his evolving needs. He feels more confident partnering with a provider that understands his specific situation and offers ongoing guidance.
This choice reflects a common real-world tradeoff: prioritizing human support and product flexibility over top-tier ratings, especially for those navigating early or nontraditional retirement paths.
Frequently Asked Questions
For immediate annuity (SPIA) payouts, the highest monthly income comes from insurers who price aggressively, often those with lower AM Best ratings. Among A-rated or better carriers, income payouts are competitive within a narrow range. Athene, MassMutual, and New York Life consistently offer strong SPIA payouts. The best way to find the highest payout is to get quotes from 3–5 carriers simultaneously through an independent broker or annuity marketplace.
Annuities are not FDIC-insured, but every state has a guaranty association that protects policyholders if an insurer becomes insolvent. Most states guarantee at least $250,000 in annuity benefits, though coverage structures and limits vary by state — some guarantee more, and a few (like California) cover a percentage of value rather than the full amount. In most cases, another insurer acquires the failed company’s contracts, and you continue receiving payments under the new carrier. Insurance company failures are rare, but this is one reason financial strength ratings matter when choosing a provider.
Yes, and many financial advisors recommend it. Spreading your annuity purchases across multiple highly rated carriers diversifies your risk and lets you match different products to different goals. For example, a MYGA from one company for guaranteed growth alongside a SPIA from another for immediate income. This strategy also keeps each contract within your state’s guaranty association coverage limits.
New York Life and Lincoln Financial both have strong lifetime income products. New York Life’s immediate and deferred income annuities consistently rank highest for payout stability and claims-paying strength.
Still have questions?

 Ready to Secure Your Future?