A $300,000 immediate annuity pays about $1,832 a month for life to a 65-year-old woman, with most payouts ranging from $1,570 to $3,023.
Where you land depends on your age when payments start, your gender and the payout type you choose. Starting later raises the monthly amount because the insurer expects fewer payments, while adding a spouse lowers it because the same money has to cover two lives.
Each check combines interest and a return of your principal, so it stays the same no matter what the markets do. Find your age and payout type in the tables below. Our figures come from Annuity.org’s analysis of Cannex data, which CBS News has cited in its coverage of annuity income. Find your age and payout type in the table below.
$300,000 Annuity Monthly Payout by Age and Type
The later you start, the bigger the monthly check, because payments are spread across fewer expected years.
| Age | Gender | Single Life | Life + 10yr Certain | Life + 20yr Certain | Joint Life (same age) | Period Certain (20 yrs) |
| 60 | Male | $1,755 | $1,734 | $1,649 | $1,570 | $1,960 |
| 60 | Female | $1,683 | $1,666 | $1,637 | $1,570 | $1,960 |
| 65 | Male | $1,911 | $1,877 | $1,768 | $1,680 | $1,960 |
| 65 | Female | $1,832 | $1,805 | $1,734 | $1,680 | $1,960 |
| 70 | Male | $2,130 | $2,048 | $1,851 | $1,802 | $1,960 |
| 70 | Female | $2,023 | $1,968 | $1,815 | $1,802 | $1,960 |
| 75 | Male | $2,497 | $2,327 | $1,927 | $2,026 | $1,960 |
| 75 | Female | $2,350 | $2,217 | $1,908 | $2,026 | $1,960 |
| 80 | Male | $3,023 | $2,611 | $1,948 | $2,354 | $1,960 |
| 80 | Female | $2,805 | $2,510 | $1,939 | $2,354 | $1,960 |
How To Read These Numbers
- Single life: pays for as long as you live.
- Life + 10 or 20 years certain: pays for life, and if you die within the guarantee period, your beneficiary gets the remaining payments.
- Joint life: pays as long as either spouse is living.
- Period certain: pays for a set number of years, then stops. It’s useful for bridging a gap, like the years before Social Security or a pension starts.
Real-World Examples: Carmen, Richard & Sydney
Here’s how age, gender and payout choice change what the same $300,000 pays.
| Carmen | Richard | Sydney | You | |
|---|---|---|---|---|
| Age | 65 | 75 | 75 | Your age |
| Payout option | Life only | Life only | Life + 10-year certain | Your choice |
| Monthly income | $1,832 | $2,497 | $2,217 | See your number → |
| Yearly income | $21,984 | $29,964 | $26,604 | Based on your answers |
| Priority | The highest income now; no legacy needed | More income while active in retirement | Lifetime income, plus payments to her beneficiary if she dies early | What matters most to you |
What the examples show:
- Age raises the payout. At 75, Richard gets about $665 more a month than Carmen at 65, because the insurer expects to make payments for fewer years.
- Gender matters. Women generally live longer, so a 75-year-old woman choosing life only would get $2,350 a month, about $147 less than Richard.
- Life only pays the most, with a trade-off. Carmen’s $1,832 a month is guaranteed for life. If she dies before collecting the full $300,000, the remaining balance stays with the insurer.
- A guarantee period protects heirs. Sydney’s 10-year certain option pays $133 a month less than life only, but it guarantees at least $266,040 in total payments to her or her beneficiary.
I think payout annuities will surge in popularity. The financial industry is good at asset accumulation but not at decumulation—converting assets into income. While there are strategies for withdrawal rates, immediate annuities offer pension-like payouts, giving retirees confidence they won’t outlive their money.
Paul Garofoli, FLMI, RICP®Regional Vice President for Individual Annuities at Standard Insurance CompanyPaul Garofoli, with 40+ years of industry expertise, serves as the Regional Vice President for Individual Annuities at Standard Insurance Company. A notable advocate, he was elected to the Board of Directors for NAFA. Garofoli holds a Bachelor’s in Political Science and Economics from the University of Massachusetts Amherst. Over 40 years of industry experience Regional Vice President for Individual Annuities at Standard Insurance Company Elected to the Board of Directors for the National Association for Fixed Annuities (NAFA)
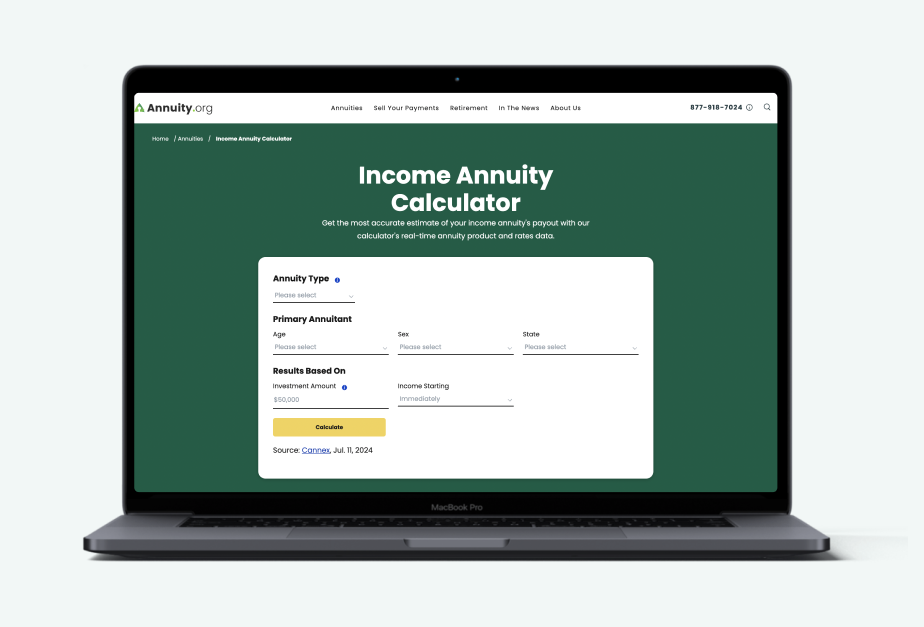
Now See What Your Savings Could Pay You
$300,000 Annuity Annual Payout Rates by Age and Type
Each percentage shows what your $300,000 pays out per year. It blends interest with principal coming back to you, so it isn’t a yield in the investment sense.
| Age | Gender | Single Life | Life + 10yr Certain | Life + 20yr Certain | Joint Life (both same age) | Period Certain (20 yrs) |
| 60 | Male | 7.02% | 6.94% | 6.60% | 6.28% | 7.84% |
| 60 | Female | 6.73% | 6.66% | 6.55% | 6.28% | 7.84% |
| 65 | Male | 7.64% | 7.51% | 7.07% | 6.72% | 7.84% |
| 65 | Female | 7.33% | 7.22% | 6.93% | 6.72% | 7.84% |
| 70 | Male | 8.52% | 8.19% | 7.41% | 7.21% | 7.84% |
| 70 | Female | 8.09% | 7.87% | 7.26% | 7.21% | 7.84% |
| 75 | Male | 9.99% | 9.31% | 7.71% | 8.11% | 7.84% |
| 75 | Female | 9.40% | 8.87% | 7.63% | 8.11% | 7.84% |
| 80 | Male | 12.09% | 10.44% | 7.79% | 9.42% | 7.84% |
| 80 | Female | 11.22% | 10.04% | 7.76% | 9.42% | 7.84% |
Most importantly:
- The payout rate climbs every year you delay starting.
- Choosing joint life trims the percentage, because the income has to stretch over two lives instead of one.
- A payout rate isn’t an interest rate. It’s the share of your $300,000 returned to you each year as income.

Ready To See Real Quotes?
Factors Impacting How Much a $300,000 Annuity Pays per Month
Several factors can influence the payout of an annuity.
Payout Factors for Annuities
- Annuitant’s life expectancy: The age and sex of the contract’s annuitant play a major role in payout calculations because insurance companies use this information to determine life expectancy. The longer you’re expected to live, the lower your payments will be, so women and younger people tend to receive lower monthly payouts.
- Payout period: The insurance company also factors in any guarantees in the contract for how long payments must continue. For example, a single life annuity will have higher payments than a joint life annuity that covers two people’s lifetimes.
- Type of annuity: Immediate annuities are the simplest type of annuity and therefore have the most predictable payouts. Most other types of annuities undergo an accumulation phase before converting to income, making returns more difficult to calculate in advance.
- Riders: A key advantage of annuities is the ability to customize a contract with riders at an additional cost. Riders like a return of premium or cost of living adjustment rider influence the annuity’s payout, as these represent additional risk to the annuity issuer.
The premium amount is one of the most important elements, as it’s usually the starting point of any annuity calculation. However, even annuities with the same premium amount can have very different monthly payouts, as the case study scenarios show.
Frequently Asked Questions
A $300,000 immediate annuity pays about $1,832 a month for a 65-year-old woman and $1,911 for a 65-year-old man, choosing life only. Depending on age, gender and payout option, most payouts fall between $1,570 and $3,023 a month, based on September 2026 quotes.
Yes. A man who buys a $300,000 life-only annuity at 60 gets about $1,755 a month, compared with $2,130 at 70 and $3,023 at 80. Insurers pay more to older buyers because they expect to make payments for fewer years.
With a life-only annuity, payments stop at death, and any remaining balance stays with the insurer. A guarantee option such as life + 10 years certain pays your beneficiary the remaining payments if you die early, in exchange for a slightly lower check: $1,805 a month instead of $1,832 for a 65-year-old woman.
A $300,000 joint annuity for a couple who are both 65 pays about $1,680 a month for as long as either spouse is living. That’s less than a single-life annuity, because the payments may have to cover two lifetimes.
The monthly payout is the dollar amount you receive. The payout rate is your yearly payments divided by your premium: 7.64% for a 65-year-old man buying a $300,000 annuity. It isn’t an interest rate, because each payment includes a return of your own principal.
They’re estimates based on immediate annuity quotes for a $300,000 non-qualified premium in Florida as of September 2026. Your actual payout depends on the insurer, your state and rates when you buy. Once you buy, the contract locks in your payment.
Still have questions?